 trading
Decoding Calendar Spreads and Raw Vega: Advanced Options Trading Strategies

Introduction
In the intricate world of quantitative options trading, multi-expiration strategies are often utilized to capture nuanced market anomalies. Among these, calendar spreads and diagonal spreads stand out as popular choices for traders looking to exploit time decay differentials. However, a superficial reading of risk parameters—specifically the Greeks—can lead to severe miscalculations.
When observing trading platforms, practitioners frequently notice a seemingly ideal structural profile: a position that is simultaneously long theta (benefiting from time decay) and long Vega (benefiting from rising implied volatility). This comprehensive technical analysis explores the structural mechanics of calendarized option strategies, deconstructs the misleading nature of nominal Vega, and introduces the concept of Raw Vega to optimize risk management.
Structural Mechanics of Calendarized Option Strategies
Calendarized option strategies encompass any position holding options across at least two distinct expiration dates on the same underlying asset. This includes:
- Calendar Spreads (Puts/Calls): Shorting a near-term (front-month) option and buying a longer-term (back-month) option at the exact same strike price.
- Diagonal Spreads (Long/Short Puts/Calls): Utilizing different expirations combined with different strike prices (e.g., diagonal long call spreads, often referred to as “poor man’s covered calls,” where the back-month option is deep in the money).
The Primary Objective: Exploiting Time Decay Disparities
The fundamental premise of a standard calendar spread is taking advantage of the non-linear acceleration of time decay ($\theta$). As an option approaches expiration, the rate of theta decay in the front-month contract increases significantly faster than in the back-month contract.
[Front-Month Expiration] ---> Rapid Theta Decay (Short Position = Profit)
[Back-Month Expiration]  ---> Slower Theta Decay (Long Position = Hedge/Value Retention)
Traders target a specific underlying price range close to the strike price at the front-month expiration, aiming to capitalize on this decay differential. Crucially, the analytical horizon for a calendar spread is not the back-month expiration, but rather the front-month expiration, at which point the entire position is typically unwound or adjusted.
Deconstructing Option Greeks in Calendar Spreads
To understand why traditional risk metrics can be deceptive, we must analyze the individual Greek components of a calendar spread (using a put calendar spread as our primary model: short front-month put, long back-month put at the same strike).
1. Delta ($\Delta$)
- Behavior: Out-of-the-money (OTM) options with longer time to expiration possess higher absolute delta values compared to OTM options with very short time horizons (as short-term OTM options rapidly converge toward zero delta).
- Position Profile: The position carries a short delta bias relative to the strike pinning target, meaning downward movement toward the strike or slight directional alignment is factored into the setup.
2. Theta ($\Theta$)
- Behavior: Front-month options exhibit significantly higher theta values near expiration than back-month options.
- Position Profile: By being short the front month and long the back month, the trader establishes a long theta profile, directly profiting from the faster erosion of the front-month premium.
3. Gamma ($\Gamma$)
- Behavior: Gamma moves in inverse tandem with theta. High front-month decay near expiration corresponds to extremely high front-month gamma.
- Position Profile: Because the front-month short option introduces high positive gamma which is subtracted from the back-month’s lower gamma, the overall net position is short gamma.
- The Risk Factor: Being short gamma leaves the trader highly vulnerable to sharp, violent price movements in either direction. A sudden breakout or breakdown away from the strike pin will result in rapid losses.
4. Vega ($\nu$)
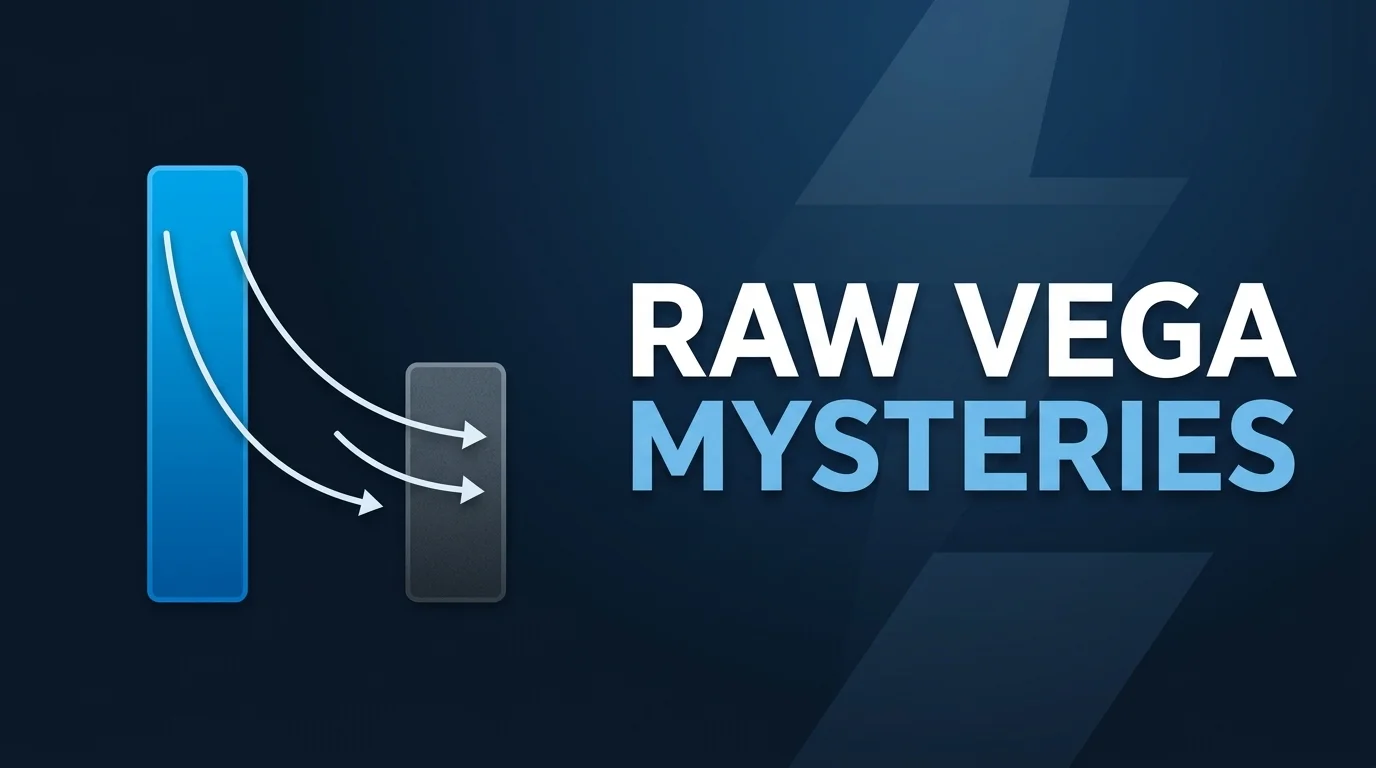
- Behavior: Vega is directly proportional to time to expiration. Front-month options have very low Vega, while back-month options carry significantly higher Vega.
- Position Profile: The back-month long option contributes substantial positive Vega, while the front-month short option subtracts a minimal amount of negative Vega. Consequently, trading platforms display a net positive Vega figure.
Advanced Options Trading in plain English | (Options Trading)
Course Specifications
- 18.5 Hours of HD Video Training: Full-length lessons in crisp 1080p resolution with English subtitles.
- Last Updated: February 2023
- File Size: 7.56 GB.
The Illusion of Nominal Vega and the Need for “Raw Vega”
The Platform Paradox
When initializing a calendar spread, retail and institutional trading platforms often report a combination of long theta and long Vega. At first glance, this creates the illusion of a flawless structure:
- If time passes and the market remains calm, you profit via theta.
- If volatility expands abruptly, you profit via Vega.
Traders feel as though they are “having their cake and eating it too.” However, this represents a fundamental misunderstanding of volatility term structures.
Why Front and Back Vegas Are Not Equal
The core discrepancy lies in the fact that implied volatility (IV) in the front and back expirations does not measure the same economic phenomenon. While correlated, the IV term structure dictates that front-month and back-month volatilities react independently and possess different baseline sensitivities to underlying price shocks (volatility skew and term structure dynamics).
Standard platform Vega aggregates these numbers linearly, treating front-month and back-month volatility changes as identical units. In reality:
- Term Structure Shocks: A shift in market sentiment does not cause front-month and back-month IV to expand by the same absolute percentage. Front-month IV is typically much more volatile and sensitive to near-term binary events (earnings, macroeconomic releases), whereas back-month IV remains anchored.
- Raw Vega Reality: When adjusting for true underlying sensitivity—often termed Raw Vega—calendarized positions frequently exhibit hidden directional volatility risk that contradicts the platform’s net positive reading.
Understanding Raw Vega ensures that options traders do not miscalculate their exposure to volatility crushes following major market events.
Conclusion
Calendarized option strategies remain powerful instruments for advanced portfolios, offering exceptional time-decay capture mechanics. However, relying blindly on platform-reported Greeks can expose traders to unexpected tail risks. By recognizing that front-month and back-month volatilities operate under distinct term structures, traders can transition from nominal risk assessment to robust, quantitative execution.